Sales Tax · Last reviewed October 3, 2026
When a SaaS Startup Needs Sales Tax Software
When does SaaS need sales tax software? Usually when you have—or are clearly approaching—collection or filing duties in multiple US states, SaaS taxability rules get hard to keep consistent, or tax ops take recurring founder hours. A practical ops heuristic is roughly five or more states with real work, or multiple hours per month on rates, exemptions, and returns. Software is rarely required at the first taxable sale if registrations and records are clean. Decide Merchant of Record vs DIY collection first, then pick calculation and filing tools.
Quick decision table
Takeaway: Match tooling urgency to nexus footprint and hours—not to competitor FOMO.
| Situation | Typical posture | Software urgency | Notes |
|---|---|---|---|
| Pre-revenue / few US customers in 1–2 states | Manual tracking + CPA check-ins | Low | Capture customer location; keep invoices exportable |
| Economic nexus approaching in several states | Nexus monitoring + registration plan | Medium | Thresholds and lookbacks differ by state (see table below) |
| ~5+ states with filings or rate logic | Calculation + filing automation | High | Spreadsheet error risk compounds with each return |
| Hours/month on tax ops (rates, exemptions, returns) | Automate calc; consider managed filing | High | Founder time usually exceeds mid-market tool fees |
| Remote employees / in-state property | Physical-nexus review + advisor | Medium–High | Can create duties below economic thresholds |
| EU/UK/AU digital sales without MoR | VAT/GST tooling or MoR rethink | High | OSS and local rules are easy to under-scope |
| Checkout via MoR that remits tax | Confirm MoR coverage; light internal monitoring | Often lower for covered channels | Direct/side channels may still create nexus |
Rule of thumb: “5+ states” and “hours per month” are operational heuristics, not legal thresholds. Legal triggers are nexus, taxability, and registration rules.
Why SaaS sales tax is unusually confusing
Takeaway: The hard part is taxability + location logic + subscriptions—not only rate tables.
Physical-goods sellers argue about shipping destination and SKUs. SaaS founders argue about whether the service is taxable at all, which address controls the tax (billing, ship-to, IP, or customer-declared location), and how seats, usage, credits, and renewals map to tax codes.
- Taxability is state-specific. Some states tax certain digital products or SaaS broadly; others exempt many business software purchases; locals can add another layer. Educational roundups in 2026 still commonly list states such as Texas, New York, Pennsylvania, and Washington among those taxing many SaaS offerings, while California generally does not tax pure SaaS at the state level—always verify current DOR guidance for your SKUs.
- B2B exemptions and certificates create workflow debt. Rate tables alone do not collect or retain exemption certificates.
- Billing systems are not tax engines by default. Stripe, Chargebee, or custom billing can store amounts; that does not mean you are registered and remitting everywhere you owe.
- International VAT/GST is a second product. US sales tax automation does not automatically finish EU OSS, UK VAT, or Australian GST.
For a broader map, see the SaaS founder compliance checklist and best accounting tools for SaaS founders.
Economic nexus snapshot (2026)
Takeaway: Most sales-tax states cluster near a $100,000 economic-nexus test; CA/NY/TX sit higher—verify each state’s lookback and includable sales.
After South Dakota v. Wayfair, Inc. (2018), remote sellers can owe collection duties based on sales volume (and, in some states, transaction counts) without a warehouse or office in the state.
South Dakota’s remote-seller pattern remains a useful official reference: more than $100,000 in gross sales into the state in the previous or current calendar year, with the separate 200-transaction test removed effective July 1, 2023 (SD DOR legislative updates; see also the state’s 2026 Sales and Use Tax Guide).
Illustrative thresholds commonly cited for remote sellers as of mid-2026 (compiled from the Sales Tax Institute economic nexus state chart, updated as of August 1, 2026). This is educational orientation—not a substitute for each DOR’s current rule:
| State (examples) | Common remote-seller dollar test | Transaction test (if any) | Notes founders miss |
|---|---|---|---|
| South Dakota, Arizona, Colorado, Illinois, many SST states | Often ~$100,000 | Many have removed older 200-txn tests (e.g. IL removed txn test effective Jan 1, 2026; KY effective Aug 1, 2026 per STI chart) | Confirm gross vs retail vs taxable sales definition |
| California | $500,000 | None (txn test removed) | High bar; SaaS may still create nexus volume even when SaaS itself is not taxed statewide |
| New York | $500,000 and >100 sales | AND test (both required) | SaaS often treated as tangible personal property for nexus math—confirm current NY guidance |
| Texas | $500,000 | None in the STI dollar summary | Gross revenue including many nontaxable/exempt sales can count toward the threshold |
| Alabama, Mississippi | $250,000-class tests | Varies / none in common summaries | Higher dollar bars than the classic $100k pattern |
| Connecticut | $100,000 and 200 transactions | AND test | Meeting only one leg is not enough |
Threshold rows summarize the Sales Tax Institute chart as of 8/1/2026 and SD DOR materials reviewed October 3, 2026. Marketplace-facilitator rules, measurement periods, and registration start dates differ—check the state before you enable collection.
Five triggers that make sales tax software worth buying
Takeaway: Buy when risk and ops cost exceed what dashboards + a CPA can safely carry.
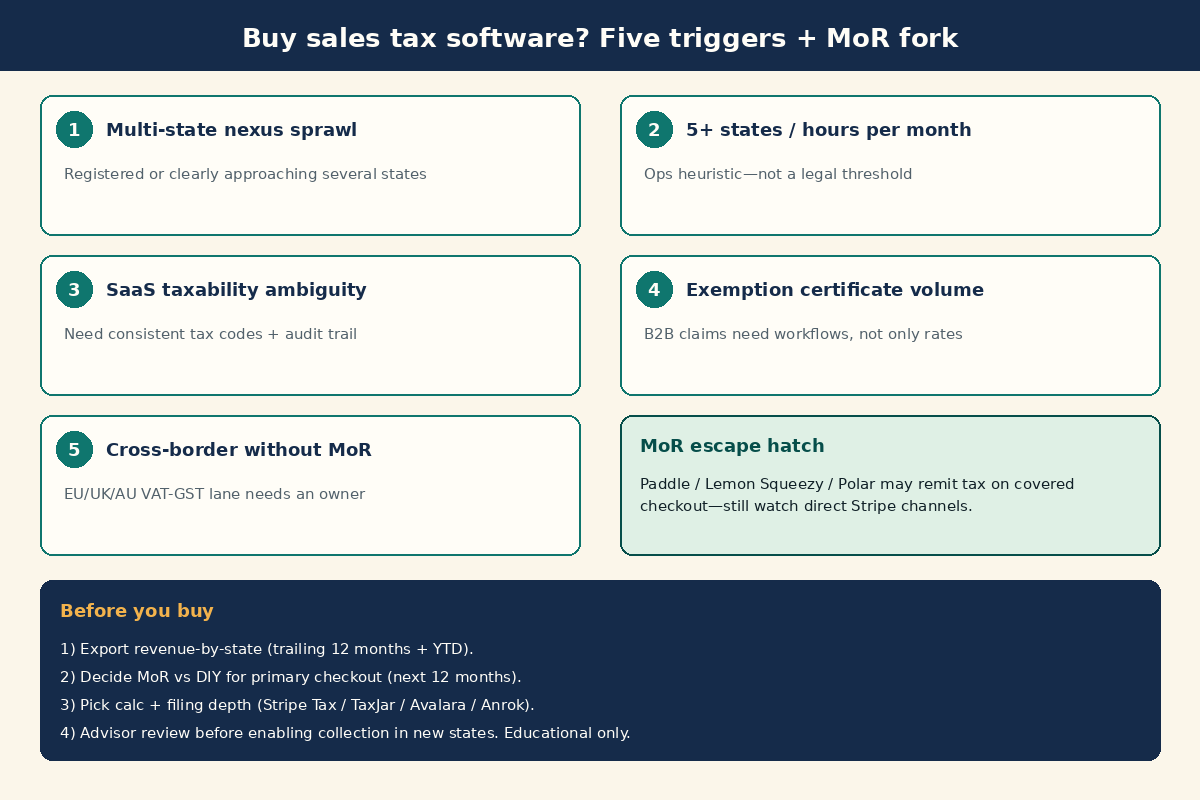
- Multi-state nexus sprawl. You are registered—or clearly approaching registration—in enough states that calendars, rates, and returns become a product.
- Five-plus-state / hours-per-month friction. Recurring founder or finance hours on tax ops usually beat “wait for a bigger ARR milestone.”
- SaaS taxability ambiguity. You need consistent product tax codes, overrides, and audit trails—not ad-hoc spreadsheet formulas.
- Exemption-certificate volume. B2B SaaS with frequent exemption claims needs certificate workflows, not only rate APIs.
- Cross-border VAT/GST without an MoR owner. Adding material EU/UK/AU consumer volume without a remitting MoR is a tooling (or MoR) decision, not a spreadsheet tweak.
Remote employees and physical nexus
Takeaway: A remote hire can create physical presence obligations even when economic-nexus dollars look low.
Economic-nexus dashboards track sales volume. They do not replace a footprint review. US states still recognize physical presence concepts: an employee working from a state, certain long-term contractors who may be argued as creating presence, inventory, or an in-state office/affiliate can trigger registration and collection duties even below that state’s economic threshold.
Founder-practical moves:
- Maintain a simple roster of where W-2 employees (and material long-term contractors) actually work—not only where your LLC is formed.
- When you hire remotely into a new state, ask counsel/CPA whether that hire creates or accelerates sales-tax (and income-tax / payroll) exposure before the first paycheck.
- Do not assume “we are under $100k into that state” closes the analysis if someone already lives and works there for you.
This is a short educational flag, not a full multi-state employment treatise. Pair it with payroll/EOR planning when you expand headcount.
Sales tax software categories and public pricing bands
Takeaway: Separate calculation, filing, nexus monitoring, and certificates—then compare public price shapes.
When founders search for sales tax software (or sales tax automation / compliance software), they usually need one or more of these layers:
- Calculation / collection at checkout or invoice time
- Nexus monitoring against state thresholds
- Returns filing and remittance (self-serve or managed)
- Exemption certificate collection and storage
- Reporting exports that accounting and advisors can trust
Public pricing snapshots (reviewed October 3, 2026). Plans and packaging change—confirm on vendor pages before you buy:
| Product | Public pricing shape (Oct 2026) | Often fits | Source |
|---|---|---|---|
| Stripe Tax | Tax Basic: 0.5% on eligible no-code taxed transactions or ~50¢ per API transaction (US public framing); Tax Complete: published monthly tiers on annual contract (US pages commonly show from about $90/mo upward by registration/filing allowances) | Stripe-native SaaS that wants calc/collection first | stripe.com/tax/pricing |
| TaxJar | Starter from $39/mo; Professional from $99/mo at the 200 orders/mo tier; AutoFile credits included with extra-credit fees listed on-page | Nexus dashboards + AutoFile across channels | taxjar.com/pricing |
| Avalara Select | Core Compliance from $79/state/mo or $799/state/yr (3-state minimum language on Avalara’s Select materials); Core + SST from $69/state/mo or $699/state/yr for qualifying sellers | Broader jurisdiction / managed returns / SST path | Avalara Select pricing materials (2026) |
| Anrok | Starter: $100 per market per month (flat); Custom: quoted per market | SaaS teams wanting calc + filing + monitoring in one per-market fee | anrok.com/pricing |
For a deeper stack comparison, read Avalara vs TaxJar vs Stripe Tax for SaaS and Anrok vs Avalara. This page stays on timing: when the category becomes worth paying for.
MoR escape hatch vs collecting yourself
Takeaway: A true Merchant of Record can own tax on covered checkout—DIY software still matters for direct channels.
If you sell through a Merchant of Record such as Paddle, Lemon Squeezy, or Polar, the MoR typically appears as the seller and remits many sales taxes / VAT/GST amounts in supported markets. That can defer or shrink the DIY sales-tax-software project for those SKUs.
It does not mean “tax problem solved forever”:
- Confirm product eligibility, supported countries, and what appears on the customer statement.
- Side channels (direct Stripe invoices, enterprise contracts, app-store hybrids) can still create nexus and filing work.
- MoR fees (often near a ~5% + $0.50 class for indie/SaaS checkouts in 2026 public pricing) trade against DIY tool + ops cost—model both.
Compare MoR paths in Stripe vs Paddle vs Lemon Squeezy and Paddle vs Lemon Squeezy vs Polar.
What to monitor before you buy software
Takeaway: Buy tools after you can export revenue-by-state and name who owns MoR vs DIY.
- Location quality: billing address, ship-to/service location, tax ID validation, and how you handle VPN/self-declared location disputes.
- Revenue-by-state (and by country): trailing 12 months and current calendar year, including refunds/credits.
- Registration inventory: where you already collect, filing frequency, and who files today.
- SKU tax codes: plan tiers, add-ons, professional services, and bundled offerings.
- Exemption policy: which B2B claims you accept and how certificates are stored.
- MoR vs DIY decision for the next 12 months of primary checkout.
Common mistake: buying enterprise-grade software before you decide who is the legal seller on the transaction. Define responsibility first; then pick calculation and filing depth.
VAT/OSS for US SaaS selling to Europe
Takeaway: Treat EU consumer VAT as a separate lane from US sales tax—or put it on an MoR.
Digital sales to EU consumers often implicate VAT rules that differ from US destination sales tax. Many non-EU sellers evaluate the Union One-Stop Shop (OSS) or local registrations; B2B reverse-charge patterns change the invoice story again. US-only spreadsheets are the wrong operating model once EU consumer volume is material and no MoR remits VAT for those SKUs.
For the dedicated walkthrough, see VAT OSS for US SaaS companies. Practical move here: split dashboards into US sales-tax lanes and international VAT/GST lanes, then assign an owner (MoR, Stripe Tax global features, or a specialist) to each.
Implementation checklist (30 days)
Takeaway: Export data → decide MoR vs DIY → pick calc/filing → advisor review before flipping collection on.
- Export 24 months of sales with best-available location fields.
- List current registrations, filing frequencies, and who files.
- Decide MoR vs DIY for primary checkout over the next 12 months.
- Pick calculation path (Stripe Tax vs TaxJar / Avalara / Anrok / other) aligned to your billing stack.
- Define tax codes for each SKU/plan; document B2B exemption policy.
- Turn on nexus monitoring for US states you sell into.
- Schedule advisor review before enabling collection in new states.
- Connect accounting mappings so tax payable does not vanish into misc clearing—see the accounting tools guide.
FAQ
1) Is there a single US sales tax threshold for SaaS?
No. Economic nexus rules are state-specific. Many states cluster near a $100,000 test; California, New York, and Texas commonly use $500,000-class tests (New York also requires a transaction count). Verify each state’s current guidance.
2) Do I need sales tax software at my first taxable sale?
Usually not. You need correct registration decisions and records. Software becomes valuable as jurisdictions and filing cadence multiply.
3) When do spreadsheets break?
Commonly around multi-state filings, frequent rate/taxability changes, exemptions, and refunds/credits. The “5+ states” and “hours per month” framing is an ops heuristic for automation ROI.
4) Does Stripe Tax replace Avalara, TaxJar, or Anrok?
Sometimes for Stripe-native calculation and collection. Filing coverage, multi-platform aggregation, per-market SaaS packaging, and enterprise workflows still push many teams toward TaxJar, Avalara, Anrok, or specialist filing partners. Compare in our 2026 tool comparison and Anrok vs Avalara.
5) Can remote employees create nexus?
Possibly. Physical presence concepts can be triggered by people or property in a state even when economic thresholds are not met. Ask a tax advisor about your footprint before treating “under $100k” as a complete answer.
6) If I use Paddle, Lemon Squeezy, or Polar, can I ignore sales tax software?
Often you can reduce DIY US/VAT scope on MoR-covered checkout—but confirm covered territories, product eligibility, and any direct billing you still run. See MoR vs payment processor.
7) What about EU VAT and OSS?
Treat VAT/OSS as its own checklist. MoR platforms can be an alternative when they support your products and countries. Start with VAT OSS for US SaaS.
8) Is this tax advice?
No. It is educational content for founders researching tooling. Your CPA or tax counsel should sign off on registrations, filings, and product taxability.
Bottom line
Buy sales tax software when nexus sprawl, SaaS taxability complexity, remote physical footprint, or filing hours make manual processes an unacceptable risk—not because every demo claims you are already late. Start from accurate location and revenue-by-state data, decide MoR vs DIY collection, then pick calculation and filing tools that match your billing stack.
Next step: compare stacks in Avalara vs TaxJar vs Stripe Tax, then deep-dive Anrok vs Avalara if you want a SaaS-focused per-market option. If MoR economics look better, read Merchant of record vs payment processor.
Related: VAT OSS for US SaaS, SaaS founder compliance checklist, Stripe vs Paddle vs Lemon Squeezy, Paddle vs Lemon Squeezy vs Polar, Start here, and Tools.